Portal partners

 Author:Mariusz Dasiewicz
After our publication last week, we present to you the second part of the article on Polish economic interests and maritime threats. Today, we focus on the security of maritime infrastructure, including terminals, pipelines, gas pipelines, naphthoports and wind farms, as well as on the necessary tools to protect Polish maritime transport and critical infrastructure in Polish maritime areas and in ports.
In the article
The previous article presented Polish maritime industry sector in a world full of threats – do we have the means to respond to this?
For several years, Poland has consistently implemented commercial and state investments in strategic transport and shipping infrastructure at sea, including in line with global trends the best way to economic development and increase its economic security (including energy). These actions should be assessed positively, but on the other hand, the fact that Poland does not have adequate tools cannot be disregarded is the protection of these investments against various forms of aggression and diversion.
Among the most important of these projects It can be indicated: Gasoport in Świnoujście (including the planned increase of its capacity to 7.5 billion cubic metres per year), planned Baltic Pipe gas pipeline, planned floating LNG terminal (FSRU, Floating Storage & Regasificatuin Unit), expansion of Gdańsk naphthoport, expansion of ports in Świnoujście (including ferry terminal, modernization of hydrotechnical solutions and external port), Gdynia and Gdańsk (external ports) or finally construction of wind farms in the Baltic.
President Lech Kaczyński's LNG terminal in Świnoujście (widest known simply as a gas port) was created in 2010-2015 (this year it was also visited by the first gas carrier with LNG transport from Qatar), and its operator is Polish LNG, a special purpose company Gaz-System, which is the key entity responsible for gas transmission in Poland. The current regasification capacity is approximately 5 billion m3 per year and is expected to increase to 8.3 billion by the beginning of 2024 according to planned investments.
The current terminal coverage indicates that this is an investment as needed as possible. After expansion, the installation will also gain new functionalities, such as the possibility of bunkering LNG-powered ships and the possibility of transferring gas to other gas carriers and railways (which gives re-export of purchased raw material). The terminal cost about PLN 3.6 billion, and its expansion is the cost of another about 2 billion.
The investment goes hand in hand with another, for the moment at a very preliminary stage of implementation, i.e. the placing in the waters of the Gulf of Gdańsk a floating LNG terminal FSRU. A similar installation has been operating since the end of 2014 with our Lithuanian neighbours in the port of Klaipeda (it has a maximum capacity of approximately 4 billion m3, but due to other infrastructure constraints it is between 2 and 3 billion).
Gaz-System is responsible for the implementation of the investment, as in Świnoujście. In September, representatives of Gaz-System, the Board of the Maritime Port of Gdańsk and the Maritime Office in Gdynia signed a letter of intent concerning the implementation of this investment. The FSRU in the Gulf of Gdańsk is expected to have a capacity of 4.5 billion m3 of natural gas per year and to start operations around 2027/28 (the investment has been discussed since 2008, it was still recently planned to be completed in 2021), and the value of the investment is expected to reach around 3 billion PLN.
The third investment in diversifying natural gas sources is the planned Baltic Pipe pipeline connecting gas infrastructure in the North Sea through the Jutland Peninsula, Fiona, Zealand and the Baltic Sea to Poland. By 2022, about 900 km of new pipelines are to be built and two (including one in Denmark) will be built and another two gas pumping stations expanded, and now all environmental permits and approvals for this project have already been issued.
The total capacity is expected to be 10 billion m3 from Denmark to Poland and 3 billion m3 in the other direction, and the blue fuel is expected to sail as early as October 2022. The value of Polish investments in the construction of this installation is about 800 million EUR (the investor and operator will also be Gaz-System). These three investments together are to form the so-called Northern Gate or the Northern Corridor, i.e. the concept of independent Poland from gas supplies from Russia to 2022 (mainly due to the activity of two companies: Gas-System and Polish Petroleum Mining and Gas Industry).
Another investment in the field of alternative sources of energy resources is the expansion of the oil terminal in Gdańsk known as kerosell. The terminal has a handling capacity of 40 million tonnes per year and is adapted to operate most oil tankers floating in the seas and oceans of the world (except the largest units exceeding 300,000 tonnes of load capacity). In 2019, oil handling in kerosene amounted to nearly 17 million tonnes and increased from 2 million tonnes compared to the previous year (which confirms the overall growth trend disrupted only by business cycles).
Interestingly, it is used not only to import raw material, but also to export oil purchased from the eastern direction, as well as to receive raw material for other countries in the region. Four vessels of 345 thousand m3 are currently under construction, and the last fifth tank of 45 thousand m3 will be put into service next year. The work will increase more than twice the terminal's storage capacity, which currently has a storage capacity of 375 thousand m3.
This is also accompanied by: the expansion of the raw material base in Gdańsk by two reservoirs of 100 thousand m3 each, as well as the expansion of fuel bases by approximately 400 thousand m3. In addition, PERN, the operator of the Polish oil transmission system, plans to expand the Pomeranian pipelines. What is very important, kerosene is the only installation in Poland that allows the intake of oil from the sea direction.
However, investment in transport maritime is not only energy, but also trade in other bulk, general goods (including mainly containers), as well as passenger transport. In order to increase the capacity and quality of services provided in all major Polish seaports, numerous investments are ongoing or planned.
Due to their scale and size listed and described here will be the only most important and most spectacular of them. The first is the new deep-water container terminal in Świnoujście, which will allow simultaneous service 2 units 400 metres long and one 200 metres long. Each year it will be possible to reload around 1.5 million TEU.
The project is currently in the market analysis phase in the form of talks with companies that express interest in the construction of this facility and have appropriate experience. As of 2019, Świnoujście has also been running works worth over PLN 200 million concerning the modernisation of the ferry terminal serving connections with Sweden – the project should be completed in 2021.
Port Gdynia also conducts numerous investment projects to better adapt its infrastructure capacity to market conditions in the form of growing competition and volume of Polish maritime trade. Among them, one could point out, for example, the widening of the entrance to the internal port, the new rotor, the construction of a new Public Ferry Terminal or the huge investments of PKP Polish Railway Lines in the access infrastructure to port areas.
However, the main point of the port's investment plan is to build a public-private partnership of the Deep-water External Port. This project is expected to last until 2028 and cost almost EUR 800 million, resulting in a port platform adapted for container handling operations, wind farm components and other cargo, as well as a LNG terminal and connected to the existing and planned land transport tissue.
However, by far the largest and most spectacular investment is the so-called Central Port, which means the expansion of the external port in Gdańsk. The whole project is expected to cost around PLN 11 billion and it is difficult to deny it the character of investments of strategic importance to the Polish economy – therefore its implementation is to be supported by the port speciality adopted in 2019 and government funds (e.g. around 3 billion for the construction of breakwaters), and the whole is to be implemented in the framework of a public-private partnership with a foreign operator of future port infrastructure. Among the main elements of the new assumption are, among others, two new container terminals, offshore terminal, LNG and passenger terminal, and a space dedicated to shipbuilding activities – all on artificial land of 400 ha. The first stage of expansion would, according to the current concepts, last until 2029, and the entire investment runs significantly in the third decade of the 21st century.
Finally, it remains, perhaps the largest in its momentum among the planned changes, namely the construction of offshore wind farms in the Baltic. The maximum potential of offshore wind energy in Poland is assessed in a differentiated manner, but it is in the range between 7.5 GW and 14 GW – in the perspective of 2030-40, as it is still difficult to judge due to technological development and the potential inclusion of further areas today for various reasons not available to offshore wind energy (MEW), but some analyses indicate around 28 GW as a maximum threshold.
At this point, there are 10 projects with a total capacity of nearly 8.7 GW, of which a significant part is to be available before 2030 (the value of these investments is to exceed PLN 18 billion by 2032). Among the main investors, one can refer to the Polish Energy Group, Polenergia (related to the property of the Kulczyk family) with its shareholder, i.e. Norwegian Equinor and PKN Orlen.
Although none of the investments has yet entered the implementation phase and it is difficult to assess fully what economic effects the construction of MEW will produce in the accompanying industries (e.g. construction of steel structures, storage, transport, assembly, servicing, construction of service ships), it will certainly be a strategic investment especially for the Pomeranian Voivodeship.
The total value of the above investments (public and private) is over PLN 45 billion, most of which will be spent in the perspective of 2030 and the whole by 2035. At the same time, this calculation concerns only the projects indicated here, and does not take into account other accompanying activities, such as railway investments in Gdynia Port.
The three main objectives of the already realised and planned investments indicated above can be defined: to increase the security and energy independence of Poland (especially from the transmission of gas and oil by land from the eastern direction), to deal with the growing needs of the Polish economy in the field of international trade and to make an energy transformation towards the "greening" of our energy mix. The question could be asked why is it so important to implement these goals?
The planned investments in infrastructure for the reception of natural gas (in LNG) are intended to increase the reception of this raw material from the sea direction from the current 5 billion m3 a year to about 22-23 billion m3, which significantly exceeds current domestic consumption of around 19 billion m3 (Please note that domestic production is approximately 4 billion m3 Each year).
This increase in import capacity from this direction will therefore allow us to: A) completely eliminate gas purchases from Russia B) a significant increase in gas re-export to other countries of region C) an increase in own consumption in the industrial energy sector in relation to less green coal, and by private consumers and entrepreneurs – we have been seeing a change in this direction for several years, thanks, among other things, to the activities carried out by the Polish Gas Company (gasification of the country, i.e. the dissemination of access to blue fuel).
In addition, the expansion of infrastructure for the reception of oil from the sea direction is expected to help reduce imports of this raw material from Russia. In 2018, 77% of black gold came from this direction, and in 2019 it was only 63%, which was possible, among other things, thanks to the increase in imports of oil from Saudi Arabia and Nigeria.
However, all of these activities are extremely easy to disrupt, especially since these energy resources are most often sent to Poland in large transports on individual ships, and therefore part of the policy of building energy independence of the Republic of Poland conducted under government auspices mainly by strategic energy companies (Orlen/Lotos, PGNiG and Gaz-System) should be the ability to effectively protect these transports.
The scale of the importance of maritime trade for the Polish economy shows the percentage of imports and exports passing through Polish seaports, which is between 35 and 50%, generating 40 billion tax and customs revenues (approximately 10% of the total revenue to the Polish budget in 2019). Sea transport exports account for about 10 to 15% of our GDP.
In 2018, almost 92 million tonnes of goods were transhipped in Polish seaports and almost 22 thousand ships entered them, and more than 600 thousand passengers were on the ferry journey. In the same year, 2 649 462 TEU was transhipped in Polish seaports (one 261 729 was unloaded and 1 387 733), equivalent to standardized 20-foot containers with a volume of approximately 39 m3. This means that over 49 million m were landed in Polish seaports in 20183 Contenerised cargo, i.e. about:
– 240 million TVs, i.e. 6 TVs per citizen of our country,
– 24 billion smartphones, i.e. 600 phones for every citizen of our country,
– 24 billion clothes (podays, shirts, dresses, sweatshirts or shirts), i.e. 200 sets for every citizen of our country,
– 4.5 million tonnes of bananas, i.e. about 600 kg per head per citizen of our country.
It is worth noting, however, that contrary to the current opinion in Polish seaports, more containerised goods were loaded than unloaded (52.3 to 47.7 percent), which shows that also the imports of goods of our economy are strongly linked to maritime trade. As with the transport of energy resources, in this case too, the vulnerability to the risks described in the first part of the article is high and steps should be taken to restore the potential of the Polish Navy in order to be able to talk about responsible increases in the volume of maritime trade.
In order to understand the importance of the MEW for the Polish energy system, it is enough to compare the level of power planned to be installed by the mid-1930s (about 9 GW – in the project of the Energy Policy of Poland to 2040 up to 11 GW by 2040) with the current level of total power of Polish energy, which is about 47 GW.
It shows that at least 15-20% of the Polish energy mix (at least in terms of installed power) can be energy from windmills in the Baltic. By comparison, 75% of electricity was generated in coal power plants in 2019, 8.75% of electricity was generated in wind power plants on land and 7.6% in gas.
Of course, the energy generated is different from the installed capacity, but given the fact that the MEW is characterized by greater stability and liquidity of production than the land windmills, it can be assumed that it will contribute to the revolutionization of the Polish energy mix (in the project of the Energy Policy of Poland to 2040 it is assumed that the MEW, together with nuclear power, will significantly reduce the share of coal power plants in the Polish electricity system – from the current level to only 28% in 2040). Today it is actually the only way to meet the EU's energy transition requirements.
For a long time, we have built our straw house, without even thinking about the dangers and challenges to our economic security generated by the sea window on the world. The first painful lessons due to our ignorance we have already done, among others, is the huge money that we paid for gas imported from Russia – fortunately this punishment was also relatively low, because there was no stopping of supplies. By drawing some conclusions, we have started to gain considerable energy independence and creating infrastructure conditions for the development of our maritime trade. Unfortunately, we seem to be waiting passively for another lesson.
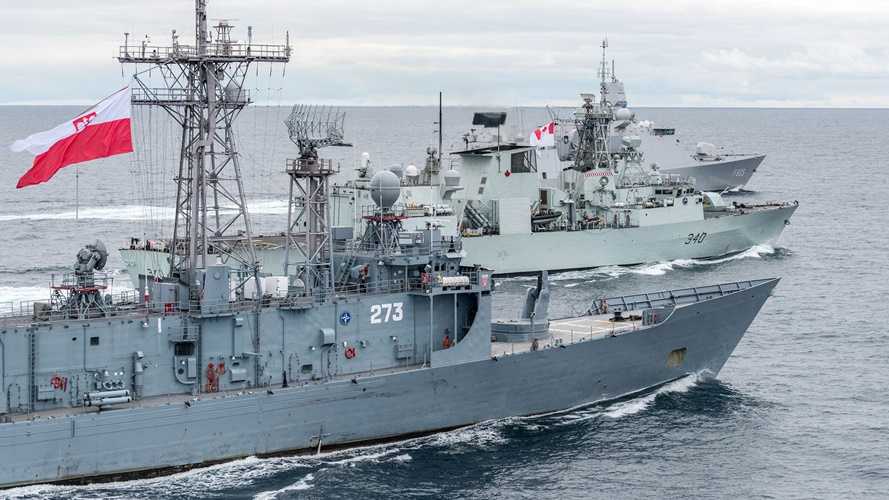
We invest in ports, terminals, increase the volume of trade by sea and at the same time completely ignore the urgent need to invest in measures to protect against threats to the functioning of this sector, i.e. our ugly duckling, the Navy, which, in the face of new threats and challenges, is the most important element of the maritime security system and properly equipped can effectively increase the level of economic and energy security of the Polish Republic – especially since it is a marginal cost compared to the investments we have written about.
In summary, it is worth to ask the question of what effects on Poland could the attack aimed at the direction of the sea, e.g. in strategic transport? ... the answer to this question as a matter of urgency we would like to hear from representatives of the government and board of maritime and energy companies (private and public). Does anyone in our country take that risk into account? Maritime transport is now the blood circulation of the Polish economy, and its slight disturbance in the absence of appropriate countermeasures, i.e. the Navy, can be disastrous for the economic functioning of the country.
Signature: ACK